Key Takeaways
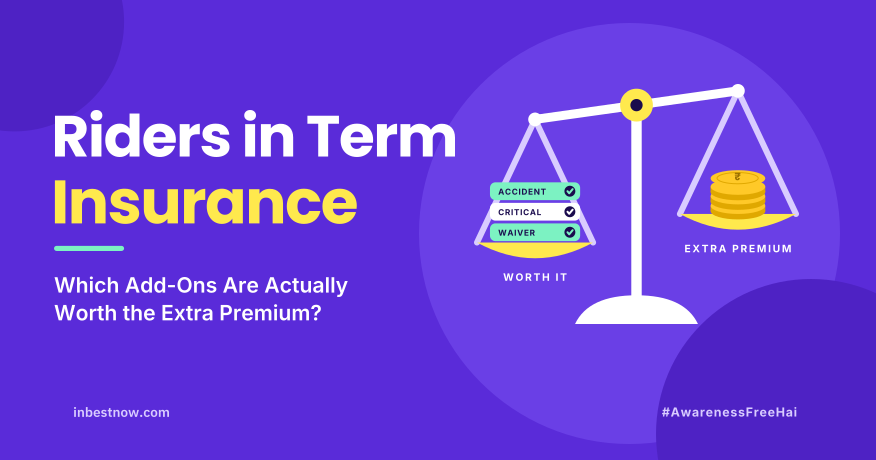
- Accidental Death Benefit and Permanent Disability riders are almost universally cost-effective — always consider adding them.
- Premium Waiver rider is inexpensive and ensures policy continuity if you become disabled — a critical safety net.
- Return of Premium rider is financially suboptimal — the 'buy term + invest the rest' strategy delivers far more.
- For CI protection above ₹25–50 lakh, a standalone policy is superior to the rider.
- Never over-rider a term plan to the point where total premiums compete with an endowment plan — keep the base premium low.
Introduction
When you buy a term plan, the insurer offers riders — add-ons that enhance coverage beyond the plain death benefit. Some are genuinely cost-effective. Others are expensive compared to standalone policies. Here is the honest, no-commission breakdown.
| Rider | What It Covers | Worth Buying? |
|---|---|---|
| Accidental Death Benefit | Additional payout if death is accidental | Yes — low cost, high value |
| Critical Illness | Lump sum on diagnosis of listed diseases | Yes — but standalone CI policy covers more illnesses |
| Permanent Disability | Premium waiver or lump sum on permanent disability | Yes — highly recommended |
| Premium Waiver | Future premiums waived on disability | Yes — cost-effective protection continuity |
| Return of Premium (ROP) | Refunds all premiums if you survive | Generally No — adds 30%–60% to premium |
| Income Benefit | Monthly income to family instead of lump sum | Situational — useful if family can't manage lump sum |
The CI Rider vs Standalone Policy
A Critical Illness rider typically covers 5–20 illnesses with a limited sum assured (₹25–50 lakh). A standalone CI policy covers 30–60 illnesses, offers higher cover, and has a dedicated claims process. For comprehensive protection, a standalone policy is superior. The rider is the lower-cost alternative when budget is the constraint.
Return of Premium: The Math Problem
ROP adds 30%–60% to your annual premium. The 'refund' you receive 30 years later has no interest component — making it worth far less in real terms due to inflation. Investing the premium difference in equity funds for 30 years delivers a corpus multiples larger than the returned premiums. ROP is a psychological comfort, not a financial advantage.
Disclaimer
Insurance is the subject matter of solicitation. Please read the policy terms and conditions carefully before purchase. Baid Solutions Insurance Broking Pvt. Ltd. is an IRDAI-registered Direct Insurance Broker (Reg. No.: 831). This content is for educational purposes only and does not constitute personalised advice.
Reviewing your term plan riders? Inbest can help you optimise coverage — visit www.inbestnow.com or call +91 9903921999.