Key Takeaways
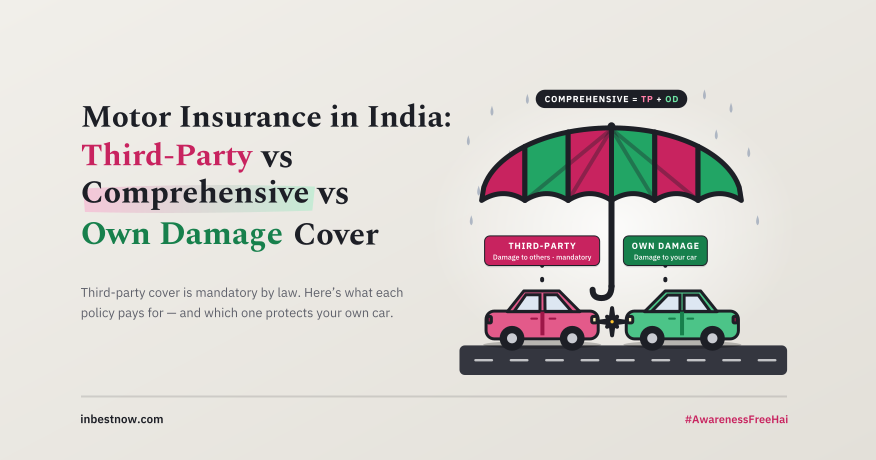
- Third-party insurance is mandatory — but it only covers damage to others; your own vehicle is completely unprotected.
- Comprehensive insurance covers both third-party liability AND own damage — the complete solution for any car owner.
- Own Damage cover is especially valuable for newer or higher-value vehicles where repair costs are significant.
- Consider Zero Depreciation and Engine Protection add-ons for new cars — they prevent large deductions at claim time.
- Review your motor insurance policy annually before renewal — compare premiums across insurers via the Bima Sugam platform or licensed brokers.
Introduction
Third-party motor insurance is mandatory by law in India. Yet most vehicle owners have no idea what it actually covers — or what it leaves completely exposed. A single accident without the right cover can cost ₹5–20 lakh in repairs and legal liability. Here is the complete breakdown.
| Cover Type | What It Covers | What It Doesn’t Cover | Legal Status |
|---|---|---|---|
| Third-Party (TP) Insurance | Damage to other person’s vehicle, property, or injury to third party | Your own vehicle damage | Mandatory — Motor Vehicles Act |
| Own Damage (OD) Cover | Damage to your own vehicle from accidents, fire, theft, natural disasters | Third-party liability | Optional — additional to TP |
| Comprehensive Insurance | BOTH Third-Party AND Own Damage in one policy | Usually excludes: accessories, electrical breakdown without cover | Optional — most complete protection |
What Third-Party Insurance Does NOT Cover
Third-party insurance — mandatory by law — covers ONLY the damage you cause to others. If your car is totalled in an accident, TP insurance pays nothing to you. If your car is stolen, TP pays nothing. If a tree falls on your car, TP pays nothing. This is the coverage gap that costs millions of Indian vehicle owners every year — because they believe ‘I have insurance’ covers everything.
Why Comprehensive Is Worth the Extra Premium
For a car valued at ₹8–15 lakh, the premium difference between TP-only and comprehensive insurance is typically ₹5,000–₹12,000 per year. For that delta, you get full own-damage coverage. A single front-end collision repair can cost ₹1–3 lakh. The insurance premium is, in most cases, well justified. After 5 years when the car’s depreciation is significant, you can reassess the OD premium vs the car’s residual value.
Add-Ons Worth Considering
Zero Depreciation cover: IRDAI allows insurers to offer this — claim settlement without deducting depreciation. Engine Protection cover: covers engine damage from flooding or hydrolock. Roadside Assistance: worth having for long-distance drivers. Personal Accident cover for owner-driver: mandatory under IRDAI rules — ensure it is in your policy.
Disclaimer
Insurance is the subject matter of solicitation. Please read the policy terms and conditions carefully before purchase. Baid Solutions Insurance Broking Pvt. Ltd. is an IRDAI-registered Direct Insurance Broker (Reg. No.: 831). This content is for educational purposes only and does not constitute personalised advice.
Want a comprehensive motor insurance review? Inbest can help — visit www.inbestnow.com or call +91 9903921999.