Key Takeaways
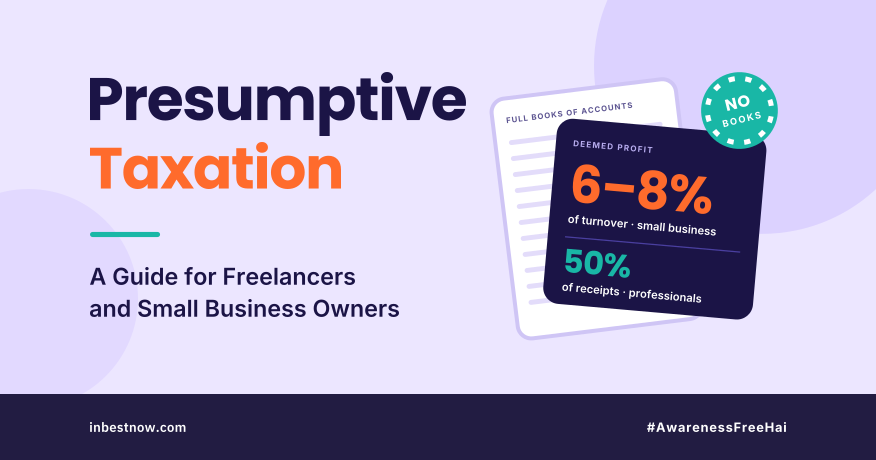
- Section 44ADA: Specified professionals declare 50% of gross receipts as income — no proof of expenses needed up to ₹75 lakh.
- Section 44AD: Small businesses declare 6% (digital) or 8% (cash) of turnover as income — up to ₹3 crore.
- No detailed books or audit required below the turnover threshold.
- Once opted for 44AD, stay in the scheme for 5 years — premature exit has consequences.
- Use ITR-4 (SUGAM) for presumptive taxation — even under this scheme, ITR filing is mandatory.
Introduction
If you are a freelancer, consultant, or small business owner, the idea of maintaining detailed books and audits every year can feel overwhelming. The Presumptive Taxation Scheme under Sections 44AD, 44ADA, and 44AE was designed precisely to simplify your compliance burden.
| Section | Who It Applies To | Presumed Income | Turnover Limit |
|---|---|---|---|
| 44AD | Small businesses — traders, manufacturers (not professionals) | 6% of digital / 8% of cash turnover | Up to ₹3 crore |
| 44ADA | Specified professionals: doctors, CAs, lawyers, architects, engineers, consultants | 50% of gross receipts | Up to ₹75 lakh |
| 44AE | Goods carriage owners | Fixed per vehicle per month | Max 10 vehicles |
How 44ADA Works for Freelancers
If you are a specified professional (IT consultants, management consultants, interior designers, and others in the prescribed list) with gross receipts up to ₹75 lakh: you declare 50% of gross receipts as taxable income. The remaining 50% is deemed expenses — no proof or documentation needed.
Example: Gross receipts ₹60 lakh → declared income ₹30 lakh → tax on ₹30 lakh at applicable slab rates.
Benefits and Limitations
Benefits:
- No detailed books of accounts.
- No audit if income declared at or above presumptive rate.
- Simple ITR-4 filing.
Limitations:
- Cannot claim actual expenses higher than the presumptive rate.
- Once opted for 44AD, you must stay for 5 years — exiting early forces standard taxation with audit for 5 more years.
Disclaimer
Mutual fund investments are subject to market risks. Please read all scheme-related documents carefully before investing. Past performance is not indicative of future results. Baid Inbest LLP is an AMFI-registered Mutual Fund Distributor (ARN: 86114). This content is for educational purposes only and does not constitute personalised investment advice. Consult a Chartered Accountant before opting for presumptive taxation.
Freelancer or business owner with tax questions? Talk to Inbest — visit www.inbestnow.com or call +91 9903921999.