Key Takeaways
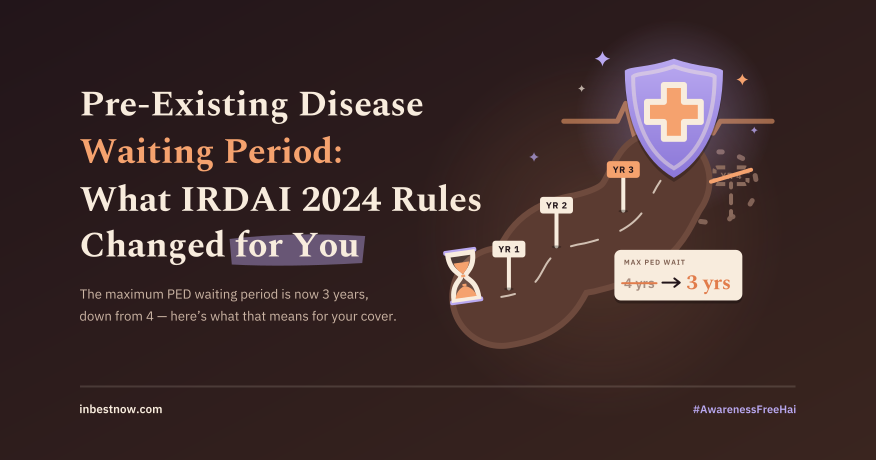
- IRDAI 2024 rules cap the maximum PED waiting period at 3 years — down from 4 years under earlier practices.
- Portability benefit: waiting period served with your existing insurer is carried forward to the new insurer — you do not restart the clock when switching.
- After the moratorium period, claims can only be rejected for fraud or material misrepresentation — a stronger protection for policyholders.
- Buy health insurance EARLY — the younger you are, the fewer pre-existing conditions, the shorter and less restrictive the waiting periods.
- Declare all existing conditions accurately at the time of application — non-disclosure is the single biggest reason for claim rejection.
Introduction
For years, a diabetic patient buying health insurance faced a waiting period of 4 years before their diabetes-related claims would be covered. IRDAI’s sweeping health insurance reforms of 2024 — which continue to reshape policies in 2026 — changed this significantly. Here is what the new rules mean for you.
What Is a Pre-Existing Disease Waiting Period?
A Pre-Existing Disease (PED) is any medical condition that existed before you bought your health insurance policy — whether diagnosed or not (if symptoms were present). Insurance companies historically imposed 2–4 year waiting periods before covering treatment related to PEDs. During the waiting period, claims related to the PED are rejected.
| Feature | Old Rules (Pre-2024) | New IRDAI 2024 Rules |
|---|---|---|
| Maximum PED waiting period | 4 years (some insurers) | Maximum 3 years for any PED |
| Moratorium period | 8 years | Reduced — check specific insurer circulars |
| Portability waiver | Waiting period may reset on portability | Waiting period served with old insurer counts toward new insurer |
| No-claim bonus | Varied by insurer | Standardised minimum requirements introduced |
| Claim rejection after moratorium | Possible in some cases | After moratorium, claim only rejected for fraud/misrepresentation |
What This Means for Common Conditions
If you have Type 2 diabetes, hypertension, or thyroid conditions and bought health insurance in or after 2024, your maximum waiting period for treatment of these conditions is now 3 years from policy inception — down from the earlier 4-year maximum. For conditions like asthma, arthritis, and PCOD, the same 3-year maximum applies. After this period, all related treatment is covered under your policy.
Disclaimer
Insurance is the subject matter of solicitation. Please read the policy terms and conditions carefully before purchase. Baid Solutions Insurance Broking Pvt. Ltd. is an IRDAI-registered Direct Insurance Broker (Reg. No.: 831). This content is for educational purposes only and does not constitute personalised advice.
Concerned about PED waiting periods in your health policy? Inbest can review your current cover — visit www.inbestnow.com or call +91 9903921999.